
Market Commentary
Renewed AI Capex Concerns Spark Rotation Out of Tech
by Sequoia Financial Group
by Sequoia Financial Group
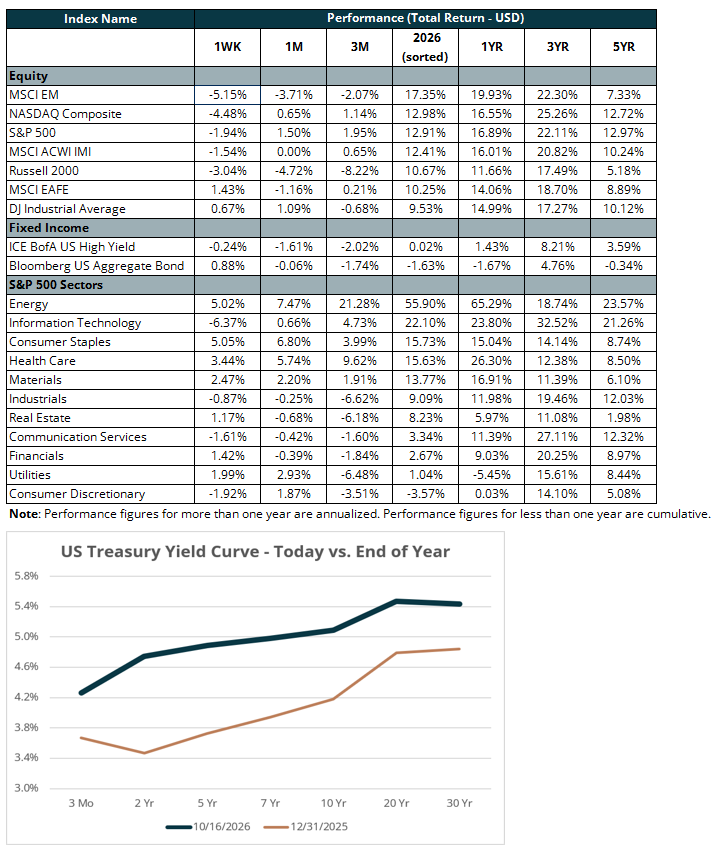
A broad retreat in technology shares set the tone for the week. The S&P 500 fell 1.9 per cent and the NASDAQ dropped 4.5 per cent, while the Dow rose 0.7 per cent as investors rotated out of tech and into more defensive sectors. Treasuries benefited from their role as a safe-haven asset, with the 10-year Treasury yield down 15 bps, helping the Bloomberg U.S. Aggregate Bond Index gain 0.9 per cent. Oil moved the other way, with WTI crude up 7.8 per cent.
The AI trade came under significant pressure as investors questioned whether the industry’s enormous spending will translate into adequate returns. Certain analysts pointed to a gap between projected AI revenue and the capital needed to build the underlying infrastructure, along with growing political and permitting hurdles for new data centers. Chipmakers fell for an eighth consecutive session on Friday, while memory makers and neoclouds (cloud providers that rent out AI computing capacity) declined sharply, with CoreWeave (CRWV) falling 15 per cent on Wednesday alone. Even solid results offered little support, as Taiwan Semiconductor (TSM) beat expectations and raised its outlook but still traded lower. Enthusiasm also cooled around Anthropic’s planned IPO. The company reportedly grew third-quarter revenue 45 per cent to $16.8 billion, a sequential slowdown after more than doubling revenue in the second quarter. Following meetings with investors, discussions reportedly centered on a valuation of around $1.5 trillion, down from earlier expectations of $2 trillion.
Inflation data offered little relief, as elevated energy costs continued to filter through to consumers. The Consumer Price Index rose 3.7 per cent from a year earlier in September, above the 3.6 per cent economists expected. Gasoline prices rose 9.1 per cent from August and are up 34 per cent over the past year, having remained elevated since the Iran conflict began in February. Despite the hot print, Fed Chair Warsh declined to signal his intentions ahead of the October meeting, and markets pulled back expectations for a hike this month. According to CME Group’s FedWatch, markets are currently pricing a 91 per cent chance the Fed raises rates at its December meeting. Elsewhere, the President’s focus shifted toward Russia and Ukraine, where the energy ceasefire he announced was quickly violated by both sides.
Third-quarter earnings season got underway with results from the largest U.S. banks, which were mixed in aggregate. Executives broadly described consumer and business activity as resilient despite higher fuel costs and borrowing rates, though some struck a more cautious tone on near-term capital markets activity. The S&P 500 is expected to report blended earnings growth of 29.4 per cent for the quarter, which combines actual results with consensus estimates for companies that have yet to report. Earnings this year have been remarkably strong, but growth has become increasingly concentrated, with Nvidia and Micron alone expected to contribute 34 per cent of the Index’s earnings growth for the third quarter.
The views expressed represent the opinion of Sequoia Financial Group. The views are subject to change and are not intended as a forecast or guarantee of future results. This material is for informational purposes only. It does not constitute investment advice and is not intended as an endorsement of any specific investment. Stated information is derived from proprietary and nonproprietary sources that have not been independently verified for accuracy or completeness. While Sequoia believes the information to be accurate and reliable, we do not claim or have responsibility for its completeness, accuracy, or reliability. Statements of future expectations, estimates, projections, and other forward-looking statements are based on available information and Sequoia’s view as of the time of these statements. Accordingly, such statements are inherently speculative as they are based on assumptions that may involve known and unknown risks and uncertainties. Actual results, performance or events may differ materially from those expressed or implied in such statements. Investing in equity securities involves risks, including the potential loss of principal. While equities may offer the potential for greater long-term growth than most debt securities, they generally have higher volatility. Past performance is not an indication of future results. Investment advisory services offered through Sequoia Financial Advisors, LLC, an SEC Registered Investment Advisor. Registration as an investment advisor does not imply a certain level of skill or training.
Renewed AI Capex Concerns Spark Rotation Out of Tech