
Market Commentary
Can AI Strength Continue to Offset Deteriorating Market Breadth?
by Sequoia Financial Group
by Sequoia Financial Group
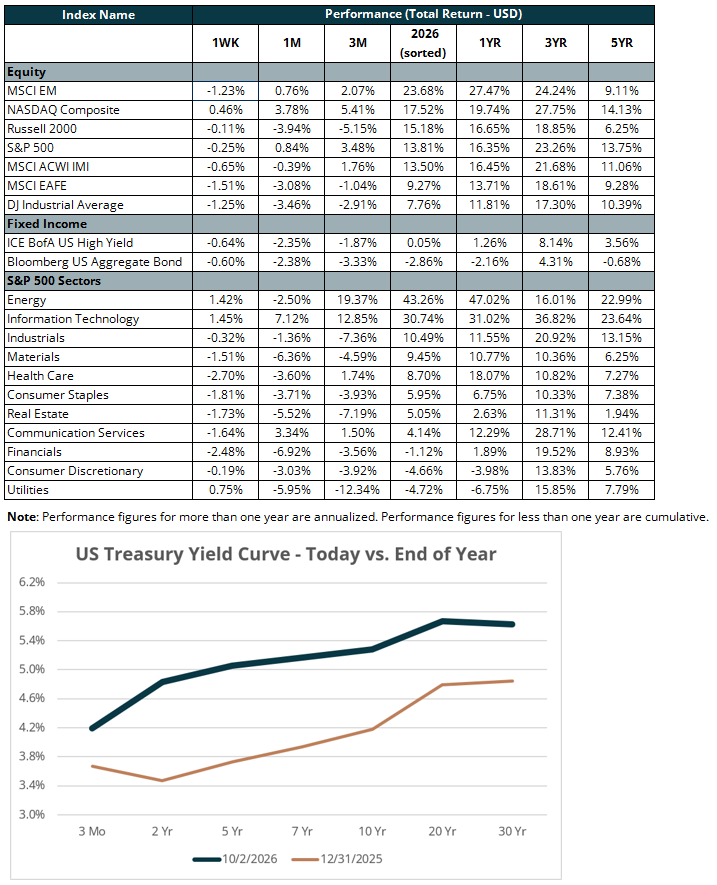
U.S. equities ended the week with mixed results. The S&P 500 declined less than one per cent to 7,722, while the Dow Jones Industrial Average declined more than one per cent to 51,177. The tech-heavy NASDAQ rose a half per cent, owing to the stability of the AI trade. Market breadth remains a weak spot. Fewer than one quarter of S&P 500 members traded above their 50-day moving averages. The equal-weight S&P 500 (ticker: RSP) fell nearly one per cent, its seventh straight weekly loss. That streak has not happened since 2022 (and before that, 2002).
Semiconductors stood apart from the pack. The PHLX Semiconductor Index (SOX) rose four per cent for a fifth consecutive weekly gain. Nvidia (ticker: NVDA) reached an all-time high ($237/share) after authorizing a record $150 billion buyback on Monday. The company also released software meant to keep AI agents inside defined limits. Together, the moves addressed worries about circular financing and rogue agents.
Friday’s “bad news is good news” narrative helped the broader equity market parse losses earlier in the week. Payrolls rose by only 29,000 against an expectation of 84,000. Interest rates initially fell and growth stocks (ticker: VUG) led their value counterparts (ticker: VTV) on Friday. Despite the drop in interest rates on Friday morning, the 10-year Treasury yield drifted back above the previous day’s close. Stocks held onto their gains on anchored optimism of a lower probability of future Fed rate hikes. On Wednesday, the Fed’s preferred inflation gauge showed core PCE at 3 per cent for August, below forecasts.
The energy sector (ticker: XLE) rose more than one per cent on the week, continuing its negative correlation pattern since the Iran war began on February 28. Energy and the broader market have moved in opposite directions on 62 per cent of trading days. Before the war, energy and the broader market moved in opposite directions on only 36 per cent of days over the trailing five years. Diesel prices have been a pressure point on inflation, and the White House is weighing an export ban to lower domestic prices.
Micron (ticker: MU) offered a counterpoint to AI concerns after Wednesday’s close. Profit reached $37.7 billion versus $3.2 billion a year ago. Revenue was $54.2 billion versus $11.3 billion. Management guided results next quarter to above consensus estimates and expects tight supply to persist through 2028. Shares gained three per cent Thursday and are up 473 per cent over the past year.
The coming week will be another test of whether AI strength can offset narrow breadth. Micron plans about $25 billion in capex over the next six months, and AI labs (e.g., OpenAI and Anthropic) need outside capital to fund their cash burns. Investors will want proof that AI spending is lifting earnings beyond the tech sector.
The views expressed represent the opinion of Sequoia Financial Group. The views are subject to change and are not intended as a forecast or guarantee of future results. This material is for informational purposes only. It does not constitute investment advice and is not intended as an endorsement of any specific investment. Stated information is derived from proprietary and nonproprietary sources that have not been independently verified for accuracy or completeness. While Sequoia believes the information to be accurate and reliable, we do not claim or have responsibility for its completeness, accuracy, or reliability. Statements of future expectations, estimates, projections, and other forward-looking statements are based on available information and Sequoia’s view as of the time of these statements. Accordingly, such statements are inherently speculative as they are based on assumptions that may involve known and unknown risks and uncertainties. Actual results, performance or events may differ materially from those expressed or implied in such statements. Investing in equity securities involves risks, including the potential loss of principal. While equities may offer the potential for greater long-term growth than most debt securities, they generally have higher volatility. Past performance is not an indication of future results. Investment advisory services offered through Sequoia Financial Advisors, LLC, an SEC Registered Investment Advisor. Registration as an investment advisor does not imply a certain level of skill or training.
Can AI Strength Continue to Offset Deteriorating Market Breadth?