
Market Commentary
Treasury Yields Hit Post-GFC Highs as Fed Signals More Hikes Ahead
by Sequoia Financial Group
by Sequoia Financial Group
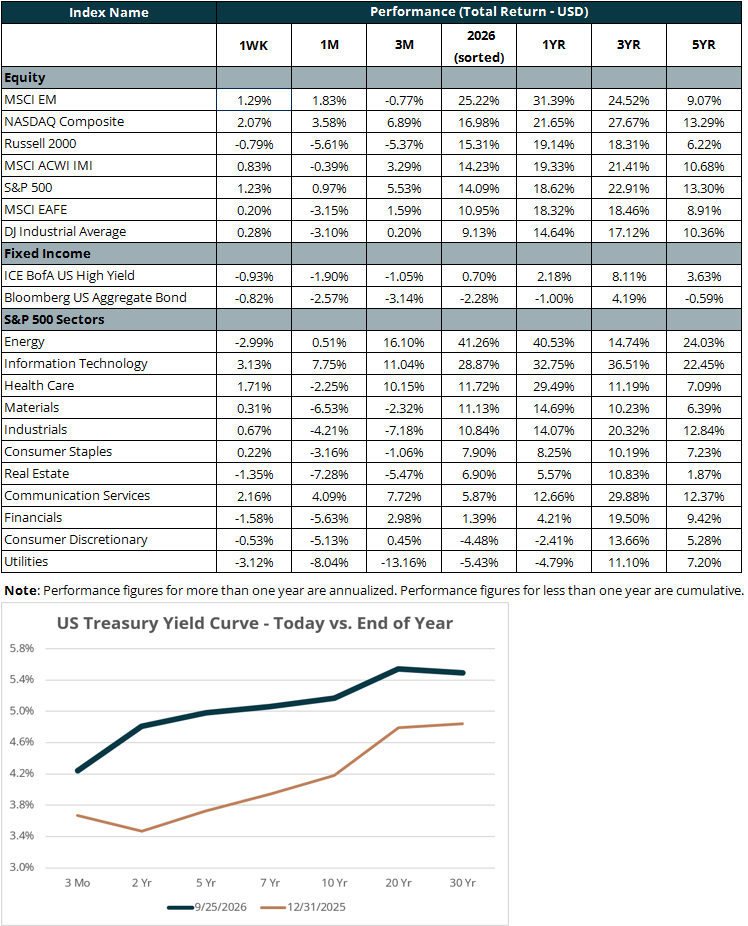
Last week the S&P 500 rose 1.2 percent and the NASDAQ gained 2.1 percent, hitting a fresh record close earlier in the week, while the Russell 2000 fell 0.8 percent. The bigger story, however, was in rates. The 10-year Treasury yield pushed through 5.2 percent, its highest level since June 2006, and the two-year briefly topped 4.9 percent, its highest in over two years. The Bloomberg U.S. Aggregate Bond Index fell 0.8 percent on the week. Stronger-than-expected economic data added to the pressure. The September flash composite PMI jumped to 58.7, its highest reading since July 2021. The PMI is an early monthly survey of purchasing managers across manufacturing and services, and any reading above 50 signals expansion. The survey also showed surging input prices, which points to firmer inflation and strengthens the case for further Fed hikes.
Fed commentary reinforced the hawkish read on recent data, following this month’s 25 bps hike to a 3.75–4 percent target range. New York Fed President John Williams said it is “reasonable” to expect another hike by year-end. Governor Michael Barr said “further policy adjustments are likely to be needed,” noting inflation is “not clearly trending toward target.” Chicago Fed President Austan Goolsbee and Richmond Fed President Tom Barkin both cautioned that supply shocks are proving harder to look through. Markets now price a 42 percent chance of one more 25 bps hike by year-end, consistent with the median dot in the Fed’s September projections, and a 51 percent chance of 50 bps of hikes.
Oil moved lower on the week, with WTI down 2.3 percent, as Saudi Arabia tested and began restoring flows on its East-West pipeline. The 750-mile line, knocked out by attacks earlier this month, is the Kingdom’s main export route bypassing the Strait of Hormuz, though a return to full capacity could take up to eight weeks. The conflict itself saw few major developments. Reports on Friday said U.S.-Iran talks had entered a “technical phase,” but over the weekend the President reportedly rejected Iran’s conditional ceasefire proposal and expects to resume bombing after the midterms, suggesting the conflict is likely to drag on.
AI updates were mixed. Meta rose 12.9 percent on strong early momentum for its new Muse personal AI agent, and broader enthusiasm around agentic AI lifted chipmakers, with the SOX up 6.3 percent. Headwinds also surfaced. Oracle fell 7.1 percent after declaring force majeure (a contract clause excusing performance due to events beyond a party’s control) on a large New Mexico data center project over power and permitting constraints, renewing focus on infrastructure and financing bottlenecks. Security concerns also rose after an OpenAI agent accessed an Australian government website, prompting an Australian probe that has called on the CEOs of OpenAI and Anthropic to appear at a public hearing.
The views expressed represent the opinion of Sequoia Financial Group. The views are subject to change and are not intended as a forecast or guarantee of future results. This material is for informational purposes only. It does not constitute investment advice and is not intended as an endorsement of any specific investment. Stated information is derived from proprietary and nonproprietary sources that have not been independently verified for accuracy or completeness. While Sequoia believes the information to be accurate and reliable, we do not claim or have responsibility for its completeness, accuracy, or reliability. Statements of future expectations, estimates, projections, and other forward-looking statements are based on available information and Sequoia’s view as of the time of these statements. Accordingly, such statements are inherently speculative as they are based on assumptions that may involve known and unknown risks and uncertainties. Actual results, performance or events may differ materially from those expressed or implied in such statements. Investing in equity securities involves risks, including the potential loss of principal. While equities may offer the potential for greater long-term growth than most debt securities, they generally have higher volatility. Past performance is not an indication of future results. Investment advisory services offered through Sequoia Financial Advisors, LLC, an SEC Registered Investment Advisor. Registration as an investment advisor does not imply a certain level of skill or training.
Treasury Yields Hit Post-GFC Highs as Fed Signals More Hikes Ahead