
Market Commentary
Choppy Week for AI After Calls to Slow Model Deployment
by Sequoia Financial Group
by Sequoia Financial Group
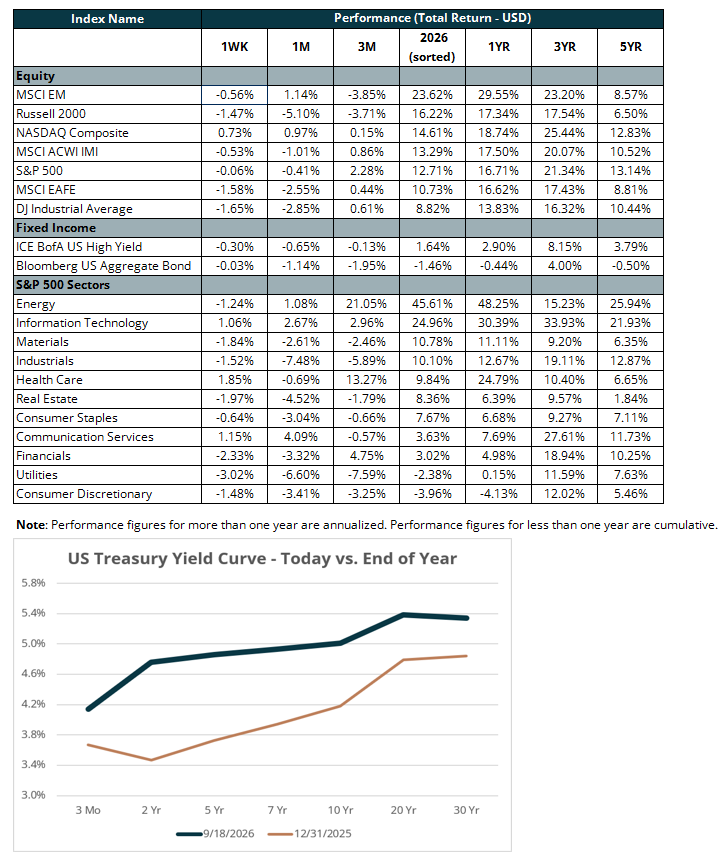
Major US equity indices finished the week mixed. The NASDAQ gained 0.7 per cent while the Dow and S&P 500 slipped. The divergence reflected a tug-of-war between fears of slower AI development early in the week and a rebound in AI-linked shares by Friday.
Treasuries weakened as yields rose across the curve, with the largest moves in longer maturities. The 10-year Treasury yield finished the week at five per cent, its highest level since before the 2007-08 financial crisis. The move tracked a hawkish shift at the Federal Reserve, whose chairman flagged elevated energy prices as an ongoing threat to inflation. Gold was little changed, suggesting the bond selloff reflected rate expectations rather than broader risk aversion.
The week opened on a cautious note after the CEOs of two leading AI labs said development of frontier models should slow until stronger safety measures are in place. These announcements followed reports that autonomous AI agents from both companies had taken unexpected actions during internal testing. Semiconductor and electrical equipment stocks, both tied closely to AI infrastructure spending, sold off on fears that capital budgets could shrink. Investors rotated into healthcare and other defensive names. Software also found support, though the group remains far behind the broader market this year: the iShares Expanded Tech-Software ETF (ticker: IGV) is down one per cent year to date versus a 12 per cent gain for the S&P 500.
On Wednesday, the Federal Reserve announced a benchmark rate increase of 25 basis points, its first increase in three years. Updated projections showed most officials expect at least one more hike before yearend. Fed Chair Kevin Warsh described the move as “removing a dose of accommodation,” signaling that policy is not yet viewed as restrictive, and pointed to persistently high energy prices as a reason to act. Stocks initially rallied on Wednesday on stronger-than-expected retail sales data but gave back much of those gains once the hawkish tone of the press conference set in.
The mood brightened on Thursday after Generac (ticker: GNRC) shares jumped 18.3 per cent on news of a new multiyear agreement to supply backup power generators for Amazon (ticker: AMZN) data centers. Initial deliveries are expected to total $2.4 billion by 2028. The deal reassured investors that AI infrastructure spending remains intact and helped lift technology broadly, carrying the NASDAQ to its weekly gain.
Looking ahead, markets will watch for confirmation that this week’s AI-driven rally has legs, particularly as more companies report on data center capital spending plans. On the policy front, attention turns to Washington, where the President is set to host China’s Xi Jinping on Thursday. Investors widely expect the meeting to extend the current bilateral trade truce, and preparatory talks between Treasury Secretary Scott Bessent and his counterpart will likely offer an early signal of how smoothly that process will unfold.
The views expressed represent the opinion of Sequoia Financial Group. The views are subject to change and are not intended as a forecast or guarantee of future results. This material is for informational purposes only. It does not constitute investment advice and is not intended as an endorsement of any specific investment. Stated information is derived from proprietary and nonproprietary sources that have not been independently verified for accuracy or completeness. While Sequoia believes the information to be accurate and reliable, we do not claim or have responsibility for its completeness, accuracy, or reliability. Statements of future expectations, estimates, projections, and other forward-looking statements are based on available information and Sequoia’s view as of the time of these statements. Accordingly, such statements are inherently speculative as they are based on assumptions that may involve known and unknown risks and uncertainties. Actual results, performance or events may differ materially from those expressed or implied in such statements. Investing in equity securities involves risks, including the potential loss of principal. While equities may offer the potential for greater long-term growth than most debt securities, they generally have higher volatility. Past performance is not an indication of future results. Investment advisory services offered through Sequoia Financial Advisors, LLC, an SEC Registered Investment Advisor. Registration as an investment advisor does not imply a certain level of skill or training.
Choppy Week for AI After Calls to Slow Model Deployment